What Every Home Buyer Should Know Before Investing in Kansas City
Kansas City keeps showing up in buyer conversations for a simple reason. It still offers price points that look workable compared with many larger metros, but the market is no longer sleepy. Recent local data shows rising list prices, solid buyer demand, and more homes on the market than a year ago, which creates a mix of opportunity and pressure at the same time.
That combination can reward smart buyers and punish casual ones. A good purchase in Kansas City depends on more than finding an attractive house at a decent price. You need to read the block, the tax picture, the school pattern, the renovation limits, and the local job base. Buyers who do that homework usually make cleaner decisions. Buyers who skip it often pay for surprises later.
Kansas City Still Offers Access, but the Easy Deals Are Thinner
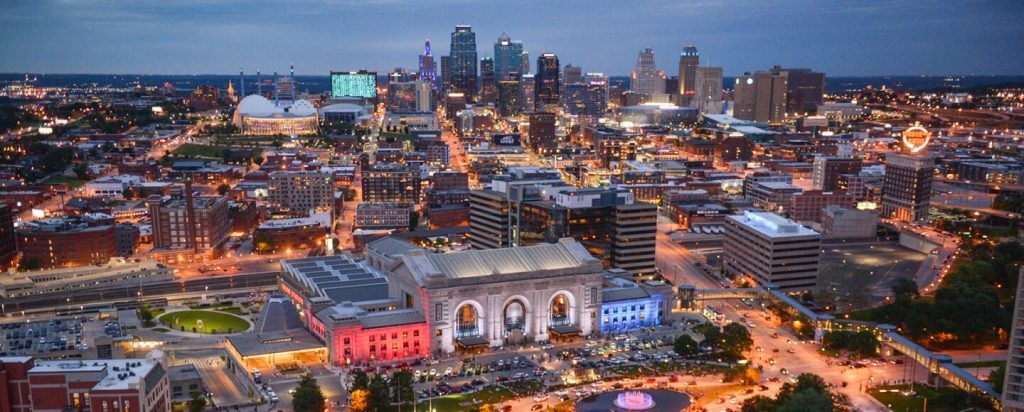
For many buyers, the first appeal is obvious. Kansas City still looks more approachable than a long list of coastal and Sun Belt markets. Realtor.com’s recent local market snapshots put Kansas City, Missouri, near a median listing price of about $255,000, with roughly 1,700 homes for sale and a sales-to-list-price ratio around 100%. That is not bargain-basement territory, but it still gives buyers room to think in practical terms.
For any prospective KC home buyer, this translates to a market where entry costs are much more manageable than in major coastal cities. Still, affordability alone does not make a deal strong. Kansas City’s hotter pockets can move fast, and recent data also shows price growth and shorter market times. A buyer who assumes every listing is negotiable simply because the city feels affordable can get caught flat-footed.
The Metro Is Really Several Markets, Not One
Kansas City is a two-state metro, and that changes the buying process in a big way. A home on one side of the state line can bring a very different tax structure, school district, municipal process, and resale profile from a similar-looking home across the line. Johnson County, Jackson County, Clay County, and Wyandotte County do not behave like interchangeable pieces of the same map. They attract different buyers, support different price bands, and come with different local rules. Official county tax and assessment systems make that plain.
That matters because broad advice about “buying in Kansas City” can miss the point. A buyer looking for strong school-driven resale demand may focus on one cluster of suburbs. Another buyer may care more about urban infill, rental demand, or access to job centers. Another may want a lower entry point and accept more block-by-block variation. Smart investors do not shop the metro as one blur. They build a short list of submarkets and compare them with discipline.
Property Taxes Can Change the Math More Than Buyers Expect
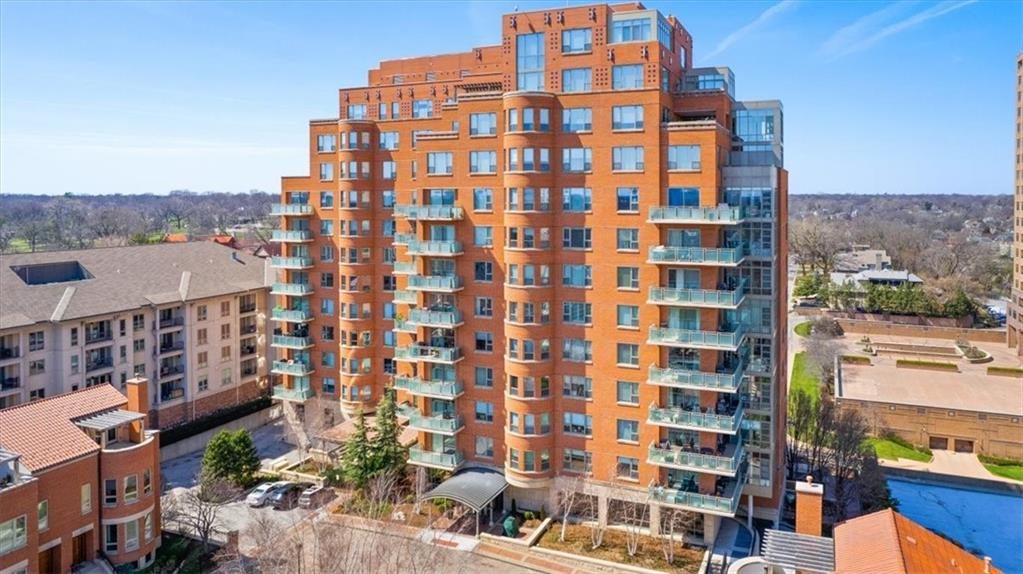
Many buyers spend weeks discussing rate locks, but far less time studying local property tax mechanics. That is a mistake. Jackson County’s assessment department states that real estate is reassessed in odd-numbered years based on current fair market value. In plain terms, that means a purchase price and a later assessed value can pull monthly ownership costs higher than a buyer expected, especially after a market upswing. Jackson County also notes that real estate tax bills are mailed in November and due by December 31.
Kansas-side buyers have their own homework. Johnson County’s property tax system gives owners tools to search current and prior bills, which helps buyers review actual tax history before they close. That kind of review matters because two homes with similar prices can carry very different annual costs once county and local tax variables hit the ledger. A buyer who focuses only on principal and interest can misread the true carrying cost from day one.
The Local Economy Still Matters More Than Marketing Language
A real estate purchase lasts longer than a seasonal market narrative. Long-term value depends in part on the metro’s ability to hold jobs, attract employers, and support wage growth. The Kansas City Area Development Council describes the region as an 18-county, two-state metro of about 2.7 million people, and its major-employers data points to a broad base instead of dependence on one single industry. That kind of diversity matters because it reduces the risk that one employer shock will hit every buyer the same way.
Labor data supports that picture. FRED, using U.S. Bureau of Labor Statistics data, shows the Kansas City metro unemployment rate at 3.9% in December 2025. That does not make every submarket equally strong, but it does suggest a metro with a relatively stable employment backdrop. Buyers who plan to hold property for years should care about that. Healthy job support tends to help occupancy, buyer demand, and resale confidence even when national housing conditions stay uneven.
Renovation Potential Is Valuable, but Only if the City Lets You Execute
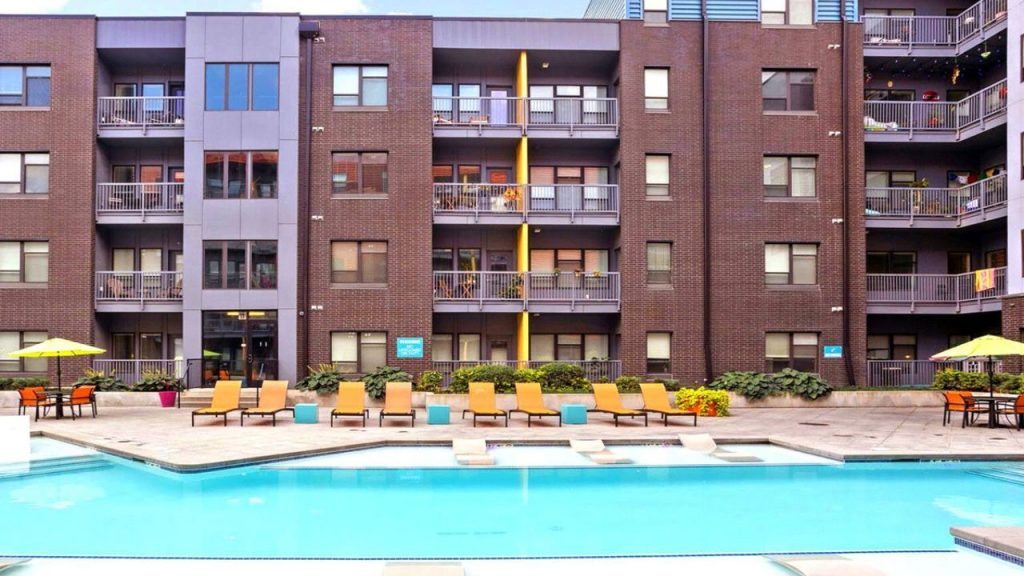
A lot of Kansas City buyers like the idea of finding an older house with upside. That can work well here. Still, projected upside means very little if zoning, permits, contractor requirements, or site constraints block the plan. Kansas City, Missouri’s permits division handles construction permits, zoning determinations, and related clearances, and the city’s development guide makes clear that permit compliance is part of the process, not an afterthought.
This is where disciplined buyers separate themselves from hopeful ones. Before buying for renovation, confirm what work needs permits, what is exempt, what setbacks or zoning rules apply, and how long approvals may take. If the investment plan depends on adding value through layout changes, additions, accessory structures, or major systems work, city process can shape the timeline and budget as much as construction pricing does. A cheap house with a complicated approval path can turn expensive in a hurry.
Hidden Risk Lives in Insurance, Flood Exposure, and Block-Level Conditions
Kansas City buyers should also think past the house itself. Flood exposure, storm risk, drainage issues, and block-level maintenance patterns can change ownership cost and resale appeal. FEMA’s floodplain guidance remains relevant for any buyer considering low-lying or water-adjacent property because improvement work on affected structures can trigger added compliance costs. That does not mean such homes should be avoided across the board. It means the due diligence has to be sharper.
The same goes for street-by-street variation. In many Kansas City submarkets, one strong pocket can sit close to a weaker one. Buyers should study not only sale comps but also vacancy signals, deferred maintenance nearby, traffic patterns, noise, planned development, and the quality of daily retail and service access. Local investment success often comes from buying the right micro-location, not merely the right ZIP code.
A Good Buy Starts With an Exit Plan, Even if You Intend to Stay
Many buyers say they are shopping for a primary home, not an investment. That sounds sensible, but it can lead people to ignore resale logic. Life changes. Jobs move. Families grow. Expenses rise. The best Kansas City purchases usually make sense from two angles at once: they work as a home today, and they remain attractive to future buyers later.
That means asking a tougher set of questions up front. Will the layout still appeal in five years? Is the location tied to durable demand drivers? Does the price leave room for appreciation after updates and carrying costs? Is the property easy to insure, easy to maintain, and easy to explain to the next buyer? In a market like Kansas City, those questions often matter more than winning a small discount during negotiation. Buyers who think ahead usually buy better.
Kansas City still gives buyers real opportunity, but it rewards careful selection more than broad optimism. The strongest purchases usually come from buyers who study submarkets closely, price taxes honestly, verify renovation rules, and treat local economic strength as part of the investment case.
That is the practical edge. Do not buy the city as an idea. Buy a specific property, on a specific block, with a clear grasp of costs, constraints, and future demand. That is how a Kansas City purchase starts looking less like a guess and more like a sound move.